Showing posts with label Employment taxes. Show all posts

Monday, November 21, 2011

Titillating tax story of the week - was stripper employed or self-employed?

This true story concerns a young lady (29) who originally trained for accountancy but then chose a more adventurous life. She worked as a stripper and lap dancer, allegedly earning upto £200k pa at Peter Stringfellow's London club.

Ms Quashie has been trying to prove that the self-employment contract that she signed when she began work was a sham. She is claiming that she was unfairly dismissed by the club even though she was ostensibly self-employed when she worked there. The corollary to this claim is that the 'employer' was avoiding employment taxes and payroll taxes on the sums paid to Ms Quashie.

Although Ms Quashie lost her original claim, an Employment Appeal Tribunal has awarded her the right to appeal that decision.

It seems that the nature of the relationship involved a number of factors suggesting that she was employed rather than self-employed. According to Ms Quashie, these included:
  • she was rostered to work for Stringfellows and there was an obligation on the club's part to allow her to work on set dates and pay her accordingly;

  • she was required to give free lap dances whenever a certain song was played;

  • the club did not allow her to work anywhere else;

  • the mutual obligations prove she was a Stringfellows employee.
This report provides further details and notes that, unsurprisingly, Stringfellows denies her claims , apparently stating that that Ms Quashie signed a contract saying she was self-employed, so cannot go to a tribunal for a job she never had.

As is well known however employers cannot evade their obligations simply by requiring employees to agree that they are self-employed. The dividing line, for tax purposes, between employed vs self-employed can be quite fine. Stringfellows is likely to win the case if they took top advice as to the wording of their contracts AND the facts support the terms thereof. In practice many 'employers' of self-employed workers fail on one or both of these tests. I would expect HMRC to take an interest in this case - for various reasons! ;-)

Anyway, given the nature of Ms Quashie's activities, this story has to receive my inaugural award for titillating tax story of the week.
Monday, August 9, 2010

Are company cars "appreciated by all"?

I was intrigued by David Cameron's reference to company cars in an interview published in the Sunday Times. He was drawing an analogy between what the Government is doing and the methodical turnaround of a failing business. It was making a lot of sense to me.

Then about half way through he noted that:
"the next step for the spending review is to identify the spending I'd describe as "acceptable in the good times, unaffordable in the bad times". To continue the business analogy, employee benefits such as company cars might fall into that category. They are appreciated by all, but if you're suffering losses for the third quarter in a row, you've got to drop them."
In principle I can follow the logic although keeping employees onside is also crucial. Indeed the analogy breaks down as cutting the provision of company cars would actually represent a cut in the employment costs of the business. If the failing business cannot afford to remunerate its workforce it should not simply cut one element of the remuneration package.

My second concern with the PM's statement was how out of date is the sentiment behind it. I thought most employers had stopped providing company cars as a perk/benefit some years back.

It was 1994 when the basis for the tax charge was changed to focus on the list price of the car (and will often be set by reference to 35% of that figure). As the increased tax charges hit employees' pockets so company cars ceased to be an attractive employment 'benefit'. The system changed again in 2002 to focus on the CO2 emissions of the car. And these days few employees appreciate the provision of company cars as a perk, once they understand the associated tax charge - other than perhaps those employees with very low CO2 emission vehicles.

The benefit in kind charge for a company car is a set % of the 'list price' ranging from 10% for cars with emissions upto 120g/km, upto a maximum of 35% for cars with emissions of 230g/km. The relevant % will be applied to the full 'list price' including including all the manufacturer options and any other extras. Thus, as the vehicle cost increases so does the tax liability.

I'd be interested to know if many people still value the old company car perk. Please let me know.

In the meantime, you can find the the CO2 emissions for most cars using the SMMT website. Another useful site for finding out the changing tax charges on company cars is UK Carline.

Monday, April 12, 2010

Election tax tease: National Insurance - The 'tax on jobs'

George Osborne and the Conservative Party have pledged to reverse a planned rise in National Insurance Contributions (NICs). This has been welcomed by business leaders and has been criticised by Labour as putting the recovery at risk.

The so called 'tax on jobs' refers to Employers' NICs. It's the tax payable by employers by reference to their workers', employees' and directors' salaries. The current tax is 12.8% and Labour have announced two 0.5% rises which are both due to take effect from April 2011 when the tax will increase to 13.8%. Incidentally, 30 years ago, in 1980, the rate was 13.7%.

It is the aggregate 1% rise in the tax that the Tories have pledged to reverse and this announcement has been welcomed by a wide range of business leaders.

Labour's plans also affect the NICs payable by the self employed and by all employees. A 0.5% rise was announced in 2008 and a further 0.5% rise was announced in 2009. The aggregate 1% rise was to take effect from April 2011. This increase too would be cancelled under Tory plans.

Those who disagree with the Tories' plan focus on the need to fund the 'tax cut'. The tax due to be raised by the 1% increase in employers' NICs is c£4.5bn pa. The Treasury estimate that the total cost of this proposal is £7bn pa. You won't find that figure in the 2010 Budget 'red book' however, as, in an effort to fool everyone, the increase in NI was contained in two separate announcements and therefore the impact and the money to be raised are in separate tables (A2 and A11). £7bn is approx the aggregate of the relevant figures in those tables. Meanwhile Peter Mandelson is claiming the cost will be £30bn. If that were the case then surely the tables should show £30bn as the tax to be raised by the increase!

The Tories say that the related adjustments mean that the total cost of their NI proposals would only be £5.6bn pa, falling to £4bn over time. In isolation it's clearly a lot of money. But it's a small fraction of the forecast deficit of £167bn in 2011. And Labour have been just as evasive as regards how this is to be cut significantly as have the Tories. As such it is hard to see any justification in arguing that this £7bn alone will "put the recovery at risk" and lead to deeper public spending cuts.

What do you think?

I wrote a related piece yesterday titled: "Election tax tease: National Insurance and Income Tax alignment."

Sunday, March 21, 2010

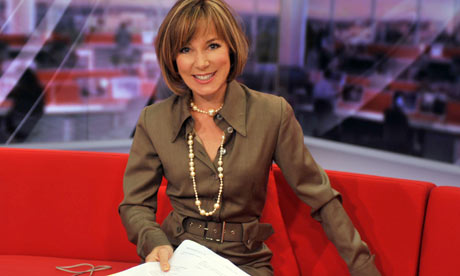
Why did the BBC's Sian Williams' appeal get to the Tax Tribunal?

Sian Williams, one of the hosts of BBC Breakfast has been in the news this week after it became apparent that she had a claim for tax relief in respect of clothes and hairstyling rejected by the Tax Tribunal.

Sian claimed that the items should be tax deductible because it was part of her job to look good on screen. Many of the media reports focused on one of the arguments used in case, that she would be prepared to read the news without clothes and only wears clothes because her employer requires it. As the Daily Express reluctantly notes however, "Mother-of-four Miss Williams has ...assured viewers that there is no danger of her actually presenting naked”.

Such claims for tax deductible clothing have long been a cause for dispute. One of the most famous cases involved a blonde Barrister (now Labour Peer), Ann Mallalieu and reached the House of Lords almost 30 years ago. She claimed tax relief for the black clothes that she was obliged to wear in court as she claimed she would never buy or wear such clothes for any other purpose. She lost the case because, the court ruled, the clothes were not purchased exclusively because she had to wear them in court, but also for the subconscious reasons of warmth and modesty.

We should bear in mind that Ann Mallalieu was self-employed and that Sian Williams was, in contrast, seeking to offset the cost of buying and laundering professional clothing etc against her employment income from the BBC. Thus her claim had to satisfy the notoriously restrictive test that the costs were involved “wholly, exclusively and necessarily" in the performance of the duties of her employment. As such her claim was almost bound to fail. As was the alternate claim being pursued that the clothes be treated as 'plant and machinery' qualifying for capital allowances.

Unsurprisingly the Tribunal first dismissed the claim for tax relief in respect of hairstyling. They noted that Sian did not have her hair done and coloured immediately before performing her duties as newsreader, and then changed back again immediately after finishing reading the news.

The failure of Sian's main claim was also quite predictable and one wonders who persuaded her that it was worth pursuing and on what grounds? Her situation was no different to many other employees (whether engaged to appear on TV or otherwise). There were not even any clear contractual obligations on Sian to acquire and wear a succession of appropriate outfits when she appeared on screen.

What do you think?

Sunday, January 3, 2010

Teach them about tax too

Does anyone else consider today's 'news' to be ironic?

Under a new personal, social, health and economic (PSHE) curriculum which becomes compulsory next year, all pupils in England, aged five to 16 will be given financial literacy lessons and taught how to save. This is commendable stuff - more so when you read the details rather than simply controversial and contrived headlines. The Mirror, for example, reports that "Children as young as FIVE will be taught how to manage bank accounts and budget." - Er. No. That's not very likely at all nor is it what the announcement says.

I prefer the Observer's headline: Children to be taught perils of debt or The Times: Pupils to be given lessons on debt. And there is the irony as it this Government that has created a new generation of graduates who are saddled with £15-£20k of debt even before they start work. It's all too easy to anticipate that these same graduates will spend upto the limit on new free credit cards. After all what's another £2k?

Ed Balls, the children schools and families secretary, is reported to have said: "It's really important that we teach our children about pensions, responsible saving and effective money management." The full departmental press release is here.

Teaching children about the difference between good debt and bad debt is important. Justifying student loans as 'good' debt will then have to follow - although I'm not sure it satisfies all the usual criteria.

One crucial element of effective money management concerns the basics of our tax system. Children don't need to know about this in detail at the age of 5 any more than they need to learn how to manage a bank account at that age. However they do need to understand some of the basics about tax before they leave school to go out to work.

A recent conversation with a hairdresser serves to ilustrate the point. She told me she is self employed but works in a salon owned by someone else. When she left school she started working in a local salon and got paid her wages each week. The expression 'cash in hand' didn't mean anything to her. As far as she knew this was normal and she did what her boss - whom she assumed to be her employer - asked of her. That was all long ago but no one had ever taught her the different tax obligations for the self employed and for employees. Or indeed the differences between being an employee and really being self employed even if working regularly for the same person.

According to the National Curriculum website, Personal, Social, Health and Economic (PSHE) education brings together personal, social and health education, work-related learning, careers, enterprise, and financial capability. In practice PSHE is intended to cover all those life lessons that we demand schools 'teach' although they are not examined so are rarely seen as a priority.

Bottom line? Even though PSHE has its detractors, please can we also ensure that we teach pre-school leavers a few key facts about the tax system?

What do you think?

Monday, February 16, 2009

No £30k exemption from tax when you leave a job

There's a common and dangerous misconception. And I saw it again in the Sunday Times yesterday, in a piece entitled: MPs plump up their ‘golden parachute’ pay. This suggested that:
"When disgraced MP Derek Conway stands down from parliament at the next election he will receive £31,645, of which the first £30,000 is tax free."
I suppose it's possible that there is a special rule for MPs (it wouldn't be the first time) but I suspect that the reporters had fallen into the all too common trap; that of assuming that the first £30,000 is invariably exempt from tax if paid in connection with one's departure from a job.

It's not. There is no automatic exemption.

What is the position then?
Firstly statutory redundancy payments are automatically free frlom tax. But the quantum of such payments is limited. So for additional amounts, there is a tax rule that means that upto £30,000 MAY be exempt from tax. It's set out in Section 401 ITEPA 2003 (previously s148 ICTA 1988). BUT this rule only becomes relevant if certain criteria are met. No one can afford to assume that their situation will automatically pass the tests.

The basic rule is that any sums paid by an employer to an employee are subject to tax if paid in accordance with a contractual obligation, if paid for work done, if paid for work to be done or if such payments are part of the employer's standard practice when someone is asked to leave their job. That's the basic rule. Only statutory redundancy payments are definitely tax free.

So when an employer makes other payments to employees the basic rule doesn't catch them. This is where s401 comes into play. It states that any other payments are taxable too - except for the first £30,000 paid in connection with the termination of employment. But this is only the case if the payment isn't taxable in full under the normal rule. And HMRC also use another rule to challenge the tax free nature of termination payments when these are paid to people aged over 50. The argument goes that the sum is taxable as an unapproved retirement benefit.

Coming back to the case of the MP referenced above I would have expected the normal rule to apply as the payoffs are contractual and (consequently) standard practice for MPs. This may well come as a bit of a shock if they were expecting to get £30,000 tax free.

What happens if you get it wrong?
Taxpayers are required to report their 'tax free' lump sum on their tax returns. The taxman invariably checks back to determine whether relevant details were properly reported by the employer. And if HMRC are not satisfied that all is correct the taxman will then seek payment of tax from the employee. For people receiving redundancy payments in early 2009, the relevant tax returns are those for the current tax year. These will not be filed until later in the year - or as late as January 2010. It could be months later before the tax demands start being issued - long after the lump sum has been spent.

Further information
Expert advice is available to help anyone who wants to learn more about how to avoid the traps here. Simply get in touch with one of the members of the Tax Advice Network who specialise in this area.

On a related issue the Low Incomes Tax Reform Group offers a fuller explanation of the tax rules on redundancy.